Insurance made easy
Friendly coverage that fits your life and budget without the hassle.
We commit to our clients and we want you to have a great experience with us.
Feeling anti social? That’s okay, just email me and we can take care of everything over email.
Lets see what discounts I can offer you today!
Protecting your family, your assets, and your future
Learn what to do after auto accidents!
*
Learn what to do after auto accidents! *
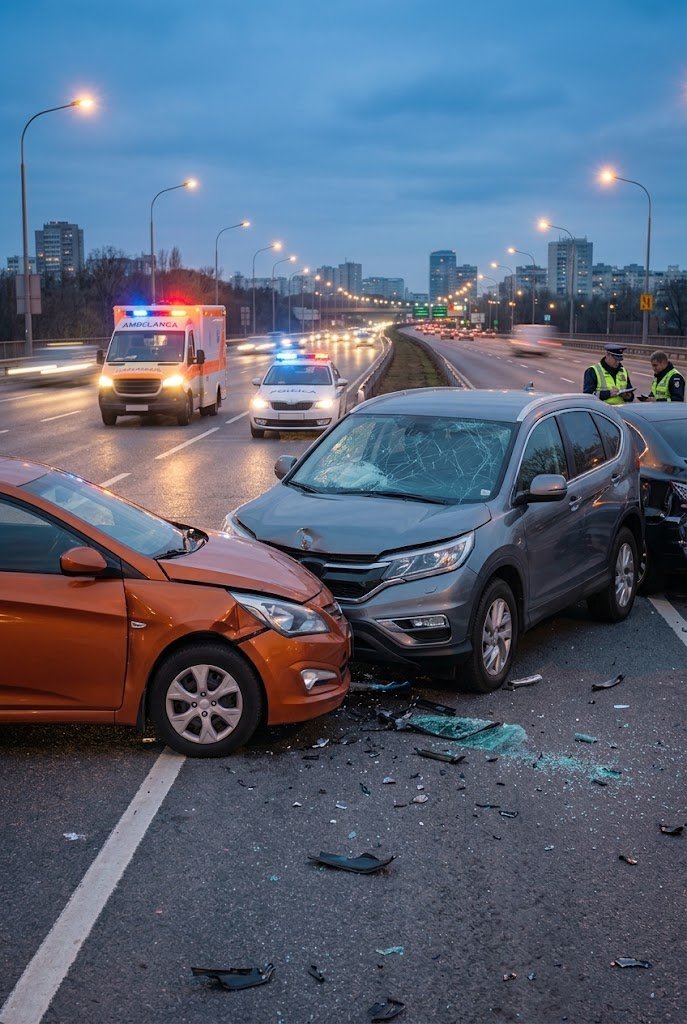
“Should I call the police after a small fender bender?”
“Should I accept an out-of-pocket payment instead of filing a claim?"
“Will insurance cover a rental car while mine is being repaired?"
"Why should I call my local agent instead of a 1-800 number?"
“Should I file a claim through my insurance or theirs?"
Give me a call today and let me answer these questions for you.
Sometimes we are unsure of the right actions to take after an accident big or small.
At Cesar Quijano’s Agency, his clients leave with the knowledge of what to do when the unexpected happens.
Our mission is to teach the ins and outs of your coverage plan. Please let us protect what matters most to you.
Why an umbrella?
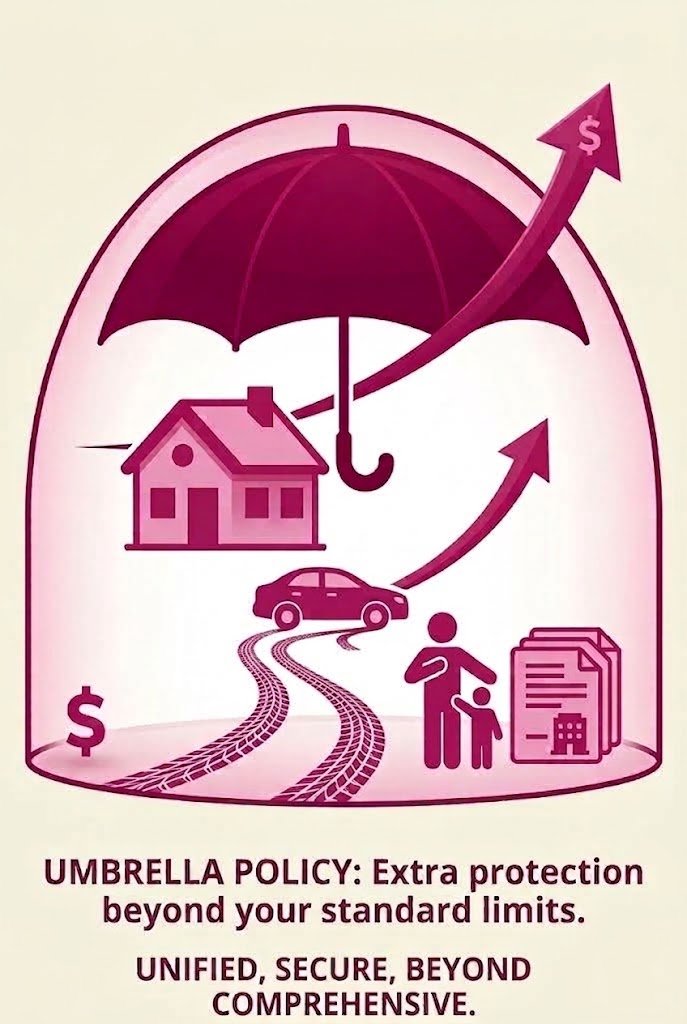
An Umbrella Liability Policy is one of the most important pieces of financial protection you can have. It provides an extra layer of liability coverage on top of your standard Home and Auto policies.
Think of it this way: your standard policies have limits. In a major lawsuit, those limits can be exceeded quickly. Once that happens, you are personally responsible for the rest, potentially putting your savings, your home, and your future income at risk. An Umbrella policy is your safety net, picking up where your other policies leave off, ensuring a catastrophic accident doesn't become a catastrophic financial loss.
Here are examples of how it protects you:
You Injure Someone While Skiing Liability isn't just for car accidents. Most Umbrella policies also extend to personal liability for events that happen anywhere. While skiing, you lose control on an icy patch and collide with another skier. The collision causes them significant injuries, including a broken leg that requires surgery and results in permanent damage, preventing them from returning to their high-paying job. They sue you for $750,000. Your Homeowners policy provides a limited amount of personal liability coverage, but not enough to cover a claim of this size.
Your Homeowners Liability Pays: $300,000 (its limit).
The Gap: $450,000.
Without an Umbrella Policy: You must find a way to pay $450,000.
With an Umbrella Policy: Your Umbrella policy covers the entire remaining balance of $450,000, protecting your assets.
Why should you carry workers comprehensive?
Operating without Workers’ Compensation can wipe out everything you’ve worked hard to build. State agencies like Utah’s Labor Commission and DOPL strictly enforce coverage laws and the consequences for skipping it are swift and severe:
Garnished Wages & Seized Assets: If an uninsured employee gets hurt, the state pays their immediate care and then comes directly after you, garnishing your personal paychecks, draining your bank accounts, and placing liens on your home to recoup every dollar.
Loss of License & Immediate Shutdown: DOPL can revoke or suspend your contractor/professional license for unlawful conduct, and state regulators can issue an instant Stop Work Order, forcing you to close your doors immediately.
Personal Lawsuits & Massive Fines: You lose all legal immunity, opening you up to personal civil lawsuits for pain and suffering, along with state fines reaching up to 3x the premium you avoided.